
Highlights
- China's rare earth prices softened modestly in March 2026 (PrNd oxide down ~3.4%, dysprosium oxide down ~3.1%), reflecting controlled calibration within a state-managed system rather than market-driven volatility.
- A two-tier global market is emerging: China controls 85-90% of processing with integrated capacity and pricing power, while a fragmented ex-China market lacks scale and liquidity despite Western policy momentum.
- Light rare earths declined more than strategically critical heavy rare earths (terbium, dysprosium), underscoring China's deliberate avoidance of price extremes that would either accelerate substitution or weaken domestic producers.
China’s rare earth market softened in March 2026—but only on the surface.
Data reveal the domestic price index averaging 273.5 points, with a high of 301.5 and a low of 252.1—a range of ~18.1%. That may suggest volatility. In reality, it reflects movement within a tightly managed system.
More telling is what sits beneath the index: most major rare earth products declined modestly, including magnet-critical materials such as praseodymium-neodymium (PrNd), dysprosium, and terbium.
Prices That Matter—And Their Subtle Signals
Using ~7.2 RMB/USD:
- PrNd oxide: ~¥592,000/t → ~$82,000/t (↓ ~3.4%)
- PrNd metal: ~¥721,000/t → ~$100,000/t (↓ ~0.5%)
- Dysprosium oxide: ~¥1.44M/t → ~$200,000/t (↓ ~3.1%)
- Terbium oxide: ~¥7.77M/t → ~$1.08M/t (↓ ~0.8%)
The divergence is notable: light rare earths softened more than heavy rare earths, reinforcing the structural scarcity—and strategic value—of elements like terbium and dysprosium.
One Market, Two Realities
The global rare earth system is no longer singular—it is splitting.
China still dominates, controlling roughly 85–90% of global processing and the bulk of magnet production. Pricing within China is shaped by quotas, industrial policy, and coordinated production.
Parallel to this, an ex-China market is emerging—smaller, fragmented, and often higher priced. It is driven by defense demand and supply chain security, but lacks scale and liquidity.
The implication is critical: Chinese domestic prices are influential—but they are not true global market prices.
Calibration, Not Correction
This is not a free-market downturn.
China has historically avoided extremes—preventing price spikes that accelerate substitution, and price collapses that weaken domestic producers. The March decline fits that pattern: controlled softening, not structural weakness.
The Western Misread
Policy momentum in the U.S. and allied nations is real. But industrial reality lags. Rare earth independence requires integrated capacity across separation, metals, alloys, and magnets—not just mining. That system remains overwhelmingly China-centric. The result: The West is building optionality. China still controls the operating system.
Bottom Line: Stability Is Strategy
China’s March pricing signals discipline, not distress.
Two markets are emerging—but only one currently has scale, integration, and pricing power. For now, China is not just participating in the rare earth market—it is still defining it.
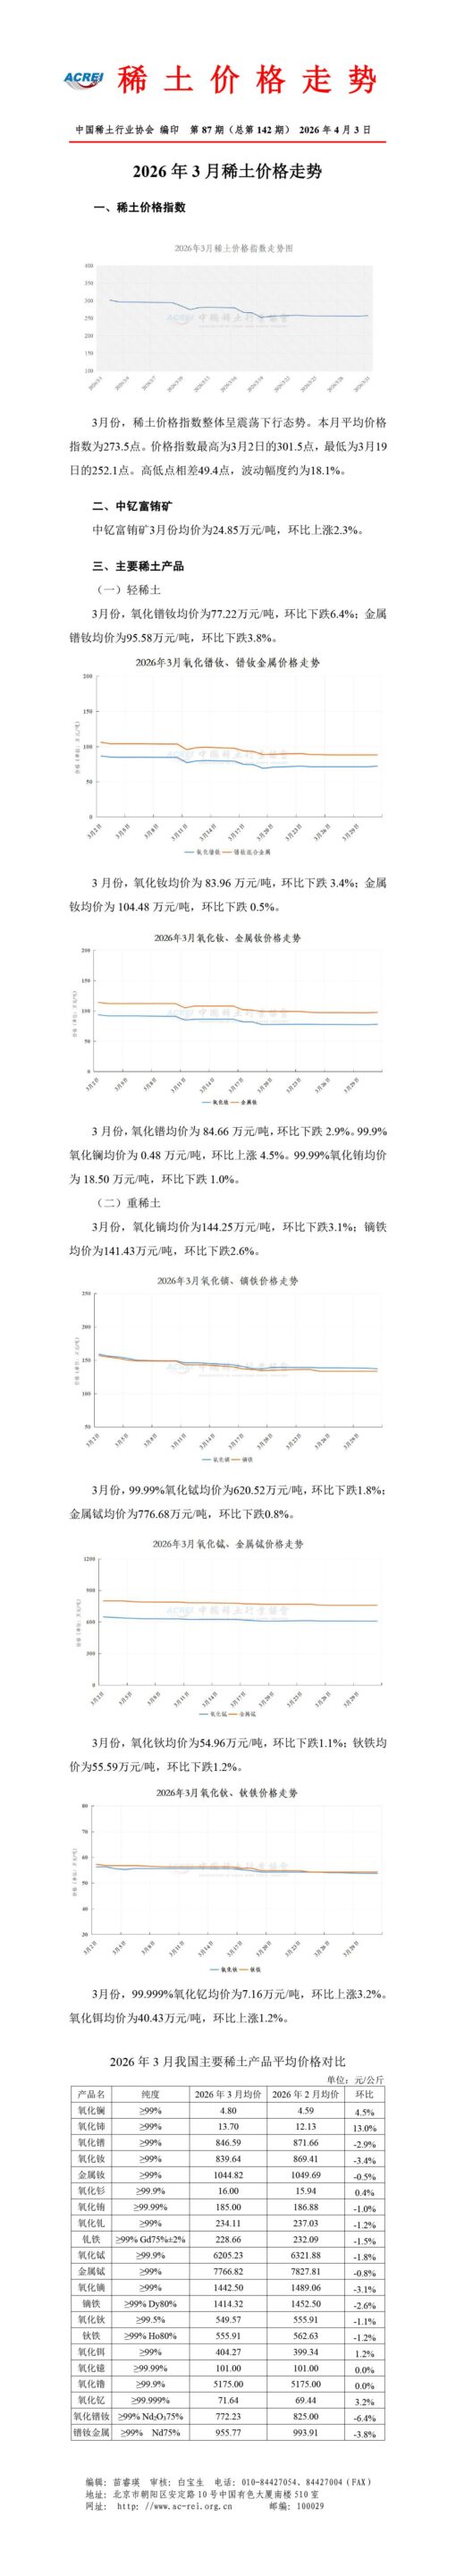
Disclaimer: This report draws on pricing data published by a Chinese industry body operating within a state-influenced system. The figures are directionally informative but may not fully reflect transparent, market-based pricing. Independent verification is recommended.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →