
Highlights
- Kazakhstan, Uzbekistan, and neighbors are emerging as strategic critical mineral provinces attracting billions in Western government and private investment.
- China's dominance in rare earth separation, metals, alloys, and magnet manufacturing remains the decisive challenge that mining alone cannot solve.
- The Middle Corridor and logistics infrastructure are becoming as strategically important as the mineral deposits themselves.
- Workforce shortages, permitting risk, and underdeveloped processing capacity are the key execution barriers separating announcements from commercial supply chains.
- Investors should distinguish between memoranda of understanding and actual offtake agreements, pilot plants and commercial-scale processing facilities.
For years, Western governments searched the globe for an alternative to China's dominance of critical minerals. The conversation centered on Australia, Canada, Africa, and Latin America. Increasingly, however, the world's attention is shifting toward a region that once sat quietly between Europe and Asia. The Caspian Policy Center's (opens in a new tab) new report (opens in a new tab), Central Asia and the New Critical Minerals Frontier: Progress in Reshaping Global Supply Chains, makes perhaps the strongest strategic case yet that Kazakhstan, Uzbekistan, Kyrgyzstan, Tajikistan, Turkmenistan, Azerbaijan, and their neighbors could become one of the most consequential mineral regions of the coming decade. Rare Earth Exchanges® agrees—with an important qualification.
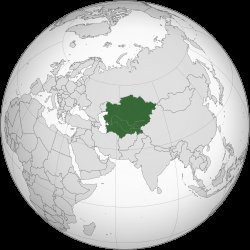
The report correctly identifies Central Asia as one of the world's emerging strategic mineral provinces. But geology alone will not determine who wins the next great mineral competition. The decisive battle remains further downstream, where China still dominates rare earth separation, metal production, alloy manufacturing, and permanent magnet fabrication. That is where the real contest begins.
A Region Returns to the Center of History
For centuries, Central Asia connected civilizations through the Silk Road. Today it finds itself at the intersection of another historic transformation—the race to secure the raw materials powering artificial intelligence, defense systems, electric vehicles, aerospace, robotics, renewable energy, and advanced manufacturing.
The Caspian Policy Center assembles an impressive collection of contributors, including Dr. Eric Rudenshiold (opens in a new tab), Kurtis Yan (opens in a new tab), Jack Halsey (opens in a new tab), Dr. Akbota Karibayeva Meyer (opens in a new tab), Samuel Ruggio (opens in a new tab), Jake Vickers, and Christopher Zrazik, to examine the geopolitical, commercial, legal, and industrial dimensions of the region's emergence.
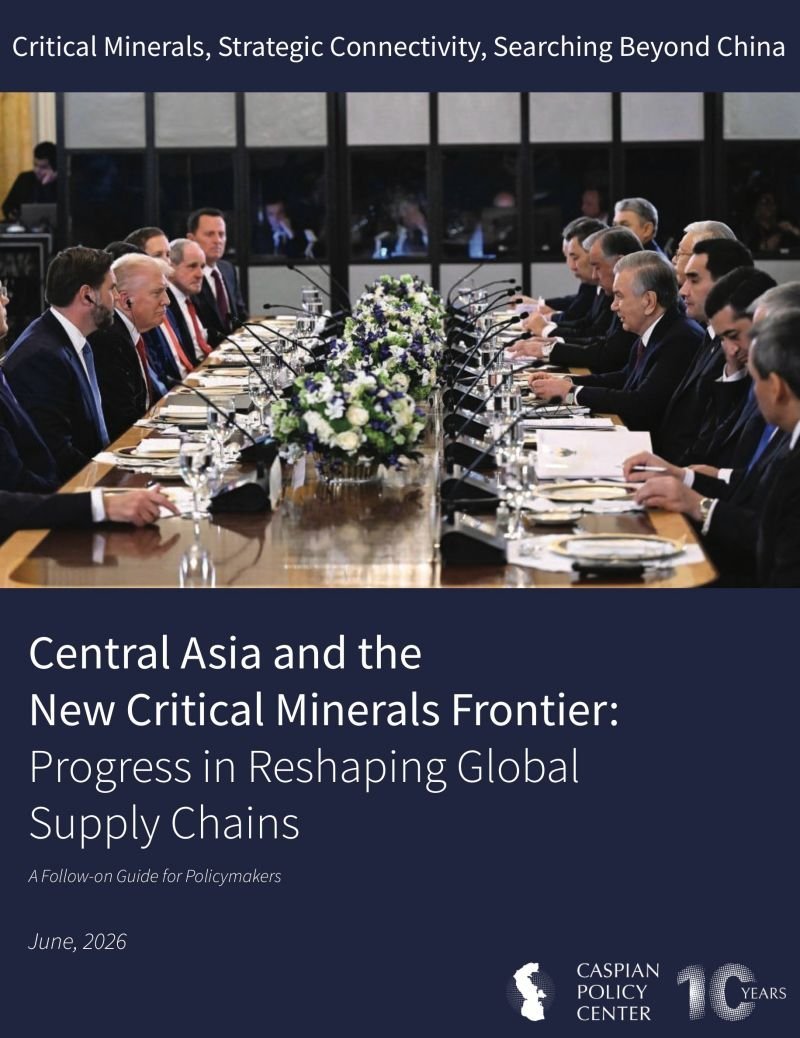
Rather than producing another catalog of mineral deposits, the report attempts something more ambitious: mapping how Central Asia could become an integrated participant in Western supply chains.
That distinction matters.
Washington Is Finally Playing Offense
Perhaps the report's greatest contribution is demonstrating how dramatically U.S. policy has evolved.
Only a few years ago, American critical mineral policy largely emphasized domestic mining. Today, Washington is building international mineral alliances at remarkable speed.
Among the initiatives highlighted are:
- Project Vault
- The Critical Minerals Ministerial
- The FORGE Framework
- C5+1 diplomatic engagement
- U.S.–EU cooperation
- Japan's expanding regional investments
- South Korean industrial participation
- Saudi Arabia's growing mining ambitions
These are no longer isolated projects. They represent the early architecture of an entirely new geopolitical minerals network. Likewise, institutions ranging from the World Bank to the U.S. International Development Finance Corporation (DFC), ADQ, and Orion Resource Partners are deploying billions toward strategic mining investments. Meanwhile, private industry is moving.
The report (opens in a new tab) references expanding interest from companies including Korea Zinc, MP Materials, Maaden, and Wabtec, alongside growing engagement from engineering firms, infrastructure developers, and institutional investors. Unlike previous commodity booms, governments are no longer merely observing markets.
They are actively attempting to shape them.
Corridors Matter More Than Borders
Mining projects succeed only if materials can reach customers. The report appropriately emphasizes the importance of transportation infrastructure, particularly the Middle Corridor (Trans-Caspian International Transport Route), which links Central Asia through the Caspian Sea into the Caucasus and Europe while bypassing Russia.
Additional initiatives—including the TRIPP Corridor, Lobito Corridor, and growing rail investments—illustrate how logistics has become strategic policy rather than simply transportation planning.
Rare Earth Exchanges has consistently argued that supply chains—not individual mines—will determine future competitiveness. In that respect, the report is entirely correct. Without reliable ports, railways, customs harmonization, financing, and permitting, mineral deposits remain geological curiosities rather than commercial assets.
The Midstream Problem Nobody Can Ignore
This is where Rare Earth Exchanges parts company with much of the current policy discussion.
The report devotes an entire chapter—"Closing the Midstream Gap"—to rare earth processing.
That chapter may ultimately be the report's most important.
Because mining is not China's greatest advantage.
Processing is.
China continues to dominate:
- Rare earth separation
- Rare earth metals
- Alloy production
- Permanent magnet manufacturing
- Industrial know-how
- Qualified engineering talent
- Commercial-scale processing capacity
Western governments increasingly understand this reality. Investors must understand it even better.
A mine producing mixed rare earth concentrate does not compete with China. A mine feeding Chinese processors often strengthens China's position. Until Central Asia—or its Western partners—can economically process oxides into metals, alloys, and magnets, much of the strategic value will continue flowing elsewhere.
Dr. Akbota Karibayeva Meyer
Capital Is Necessary. Confidence Is Essential.
Another strength of the report lies in its discussion of investment barriers.
Dr. Akbota Karibayeva Meyer (opens in a new tab) correctly argues that success depends upon far more than discovering resources.
Central Asia must continue improving:
- Mining law
- Investor protections
- Workforce development
- Geological transparency
- International reporting standards
- Environmental governance
- Technical education
- Commercial financing
The report also recognizes the importance of globally accepted reserve reporting standards such as CRIRSCO, helping investors evaluate projects using internationally recognized methodologies.
This institutional work rarely generates headlines. Yet it often determines whether billions of dollars ever arrive.
The Workforce Challenge
Supply chains ultimately depend on people.
Mining engineers.
Metallurgists.
Chemical engineers.
Process specialists.
Environmental scientists.
Equipment operators.
The report's examination of workforce development deserves particular attention because talent shortages increasingly threaten Western mineral strategies just as much as capital shortages do.
China spent decades building this human capital. Replicating it cannot happen overnight.
Investors Should Watch Execution, Not Announcements
Perhaps the greatest value of the Caspian Policy Center report is that it moves beyond political slogans.
It recognizes that successful mineral strategies require integrated ecosystems.
Yet investors should remain disciplined.
- Announcements are not production.
- Memoranda of understanding are not offtake agreements.
- Pilot plants are not commercial processing facilities.
- Rail corridors are not functioning supply chains.
- And mines alone do not produce strategic independence.
The world has entered what Rare Earth Exchanges calls the Great Powers Era 2.0™—a period in which minerals have become instruments of national security as much as industrial production.
Central Asia unquestionably possesses world-class geological potential.
The question investors must ask is whether governments, capital markets, technology providers, and industrial partners can build the missing layers between ore bodies and finished magnets before geopolitical timelines outpace commercial development. That—not the rocks beneath the ground—will determine whether Central Asia becomes the next great critical minerals success story or simply another supplier of raw materials to someone else's industrial empire. For now, the opportunity is enormous. The execution challenge may be even larger.
REEx Connect—Central Asia
| Country | Key REE & Critical Minerals | Major Projects & Initiatives | Current Status | REEx Assessment |
|---|---|---|---|---|
| Kazakhstan | Uranium, rare earth elements (exploration), beryllium, tantalum, niobium, titanium, tungsten, copper, chromium, manganese, lithium | National critical minerals strategy; expanded geological mapping; development of the Middle Corridor (Trans-Caspian International Transport Route); modernization of rail infrastructure, including procurement of Wabtec locomotives; cooperation with the U.S., EU, Japan, and South Korea | The region's most mature mining jurisdiction with established uranium and base-metals industries. Rare earth projects remain largely at the exploration and evaluation stage. Downstream processing is limited | ★★★★★ Regional leader. Kazakhstan has the strongest combination of geology, infrastructure, and foreign investment. The greatest commercial opportunity lies in attracting rare earth separation, metals, and alloy production |
| Uzbekistan | Copper, uranium, tungsten, molybdenum, graphite, lithium potential, rare earth occurrences, gold | Mining-sector reforms; expansion of geological surveys; modernization of the Almalyk Mining and Metallurgical Complex (AMMC); increasing partnerships with the U.S., EU, Japan, and South Korea | Rapidly improving investment environment with significant government support and exploration activity. Copper remains the dominant commercial opportunity | ★★★★☆ Emerging powerhouse. Uzbekistan is one of the region's fastest-improving mining jurisdictions. Rare earth potential is promising but remains secondary to copper and uranium |
| Kyrgyzstan | Rare earth occurrences, antimony, tungsten, tin, bismuth, gold, critical minerals | Government efforts to attract foreign investment; expanded geological assessment; potential participation in regional logistics and processing initiatives | Significant geological potential but constrained by political uncertainty, permitting risk, and limited infrastructure | ★★★☆☆ High-risk exploration opportunity. Attractive geology but requires greater policy stability before major Western investment is likely |
| Tajikistan | Antimony, tungsten, fluorspar, silver, rare metals, possible rare earth potential | Mining-sector development initiatives; regional transport integration; hydropower expansion that could eventually support energy-intensive mineral processing | Underdeveloped mining ecosystem despite substantial mineral endowment. Infrastructure and financing remain major constraints | ★★★☆☆ Specialty critical minerals play. Antimony could become strategically important as Western buyers seek alternatives to Chinese supply |
| Turkmenistan | Potash, bromine, sulfur, magnesium, iodine, possible lithium and rare earth potential | Caspian logistics initiatives; regional transportation integration; economic diversification beyond hydrocarbons | Mining remains secondary to the country's oil and gas sector. Public information on exploration remains limited | ★★☆☆☆ Long-term optionality. Strategic geography currently outweighs demonstrated critical-mineral development |
| Azerbaijan | Copper, gold, molybdenum, cobalt potential, aluminum feedstocks, possible rare earth exploration | Expansion of the Middle Corridor; modernization of the Port of Baku and Caspian logistics; growing EU strategic partnership; renewable-energy infrastructure | Increasingly important as a logistics and industrial hub connecting Central Asia to Europe rather than as a major mineral producer | ★★★★☆ Critical logistics hub. Azerbaijan's strategic value lies in enabling resilient Eurasian supply chains and potentially hosting downstream industrial investment |
Regional Initiatives
| Initiative | Principal Participants | Importance |
|---|---|---|
| Middle Corridor (Trans-Caspian International Transport Route) | Kazakhstan, Azerbaijan, Georgia, Türkiye, EU | The principal non-Russian trade corridor linking Central Asia with European markets |
| Project Vault | USA | U.S. initiative to accelerate financing and development of strategic mineral supply chains |
| FORGE Framework | USA & Partners | Expands cooperation on resilient critical mineral supply chains. |
| Critical Minerals Ministerial | U.S. Department of State and international partners | Coordinates international policy on strategic minerals and investment |
| C5+1 Critical Minerals Dialogue | United States plus Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan, and Uzbekistan | Framework for expanding investment, technical cooperation, and geological collaboration |
| EU Global Gateway | European Commission | Infrastructure and connectivity investments supporting diversified critical mineral supply chains |
| Tokyo Declaration | Japan and Central Asian governments | Expands Japanese financing, technology transfer, and resource cooperation |
| DFC–ADQ–Orion Resource Partners Initiative | U.S. International Development Finance Corporation, ADQ, Orion Resource Partners | Financing platform intended to mobilize up to $1.8 billion for strategic mining investments |
| World Bank, EBRD, and ADB Programs | World Bank, European Bank for Reconstruction and Development, Asian Development Bank | Support geological surveys, regulatory modernization, transportation infrastructure, and mining-sector development |
Final Thoughts
The Caspian Policy Center has produced one of the most comprehensive assessments to date of Central Asia's emerging role in critical minerals. Its greatest strength is recognizing that geopolitics, infrastructure, finance, workforce development, and industrial policy must evolve together. Where Rare Earth Exchanges extends the analysis is on the decisive importance of the mine-to-magnet supply chain. Until commercial-scale separation, metals, alloys, and magnet manufacturing are established outside China, diversification remains incomplete. Central Asia has the geology to reshape global supply chains. Whether it develops the industrial ecosystem to match remains one of the defining investment questions of this decade.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →