
Highlights
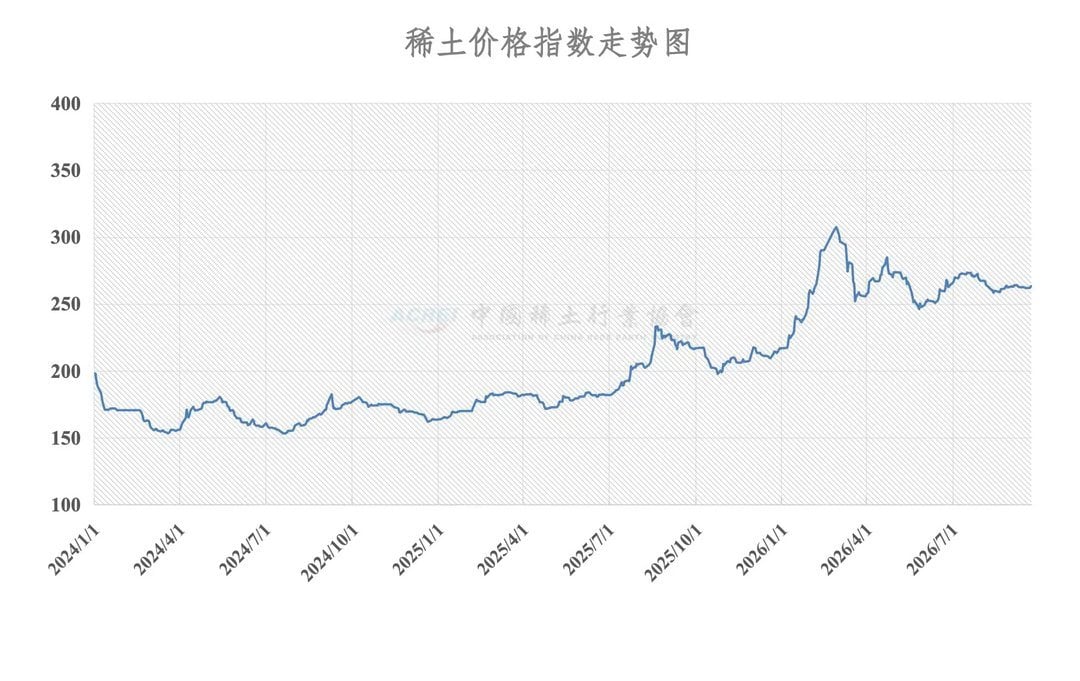
- China's September 22 Rare Earth Price Index reached 263.4, with thulium and NdPr products rising while most quotes held flat.
- Western strategy focuses on NdPr, dysprosium, and terbium, leaving a critical blind spot for yttrium, holmium, erbium, thulium, ytterbium, and lutetium.
- Lutetium oxide is quoted at ¥4,950–5,150/kg in China, yet ex-China availability is described as extremely thin and bespoke.
- The Pentagon has established price floors for NdPr, Dy, and Tb via specific contracts, but no commercial architecture exists for exotic rare earth heavies.
- Downstream disruption from rare earth supply chain vulnerability has been estimated at up to $10 trillion by Rare Earth Observer.
The China Rare Earth Industry Association reported its September 22 Rare Earth Price Index at 263.4, with most quoted products flat but thulium and NdPr products rising. The headline number masks the more consequential story: beyond dysprosium and terbium, Western industry has remarkably little reliable access to yttrium, holmium, erbium, thulium, ytterbium, and lutetium. For several of these elements, finding qualified material can matter more than its theoretical price.
REEx Insight: The Periodic Table Has a Long Tail—and China Owns Much of It
Western rare-earth strategy understandably revolves around NdPr for magnets and Dy/Tb for high-temperature NdFeB. But that focus creates a blind spot. China's September 22 sheet quotes Ho oxide at ¥631.9–651.9/kg ($94.79–97.79), Er oxide at ¥661.9–681.9 ($99.29–102.29), Yb oxide at ¥92–112 ($13.80–16.80), Lu oxide at an extraordinary ¥4,950–5,150 ($742.50–772.50), and Y oxide at only ¥58–62 ($8.70–9.30). Those prices reveal radically different abundance and demand economics—but they do not tell a Western buyer whether material can actually be procured.
That is the deeper vulnerability. Rare-earth mines do not produce elements according to Western demand. They produce a geological basket. Building an independent NdPr business therefore does not automatically create commercially viable Ho, Er, Tm, Yb, or Lu supply. Their low concentrations, tiny markets, complicated separation circuits, and uncertain offtake make dedicated Western capacity difficult to finance.
The paradox is brutal: the smaller the market, the weaker the economics for building independent supply—and potentially the greater the strategic vulnerability when China controls separation. Rare Earth Exchanges® has pointed out that Rare Earth Observer has calculated the downstream disruption to potentially reach $10 trillion.
The Strategic Basket
| Product | China ¥/kg | China US$/kg* | Ex-China reality |
|---|---|---|---|
| NdPr oxide | 725.5–745.5 | $108.83–111.83 | ~$140 reference; deeper market |
| Dysprosium oxide | 1,410–1,450 | $211.50–217.50 | ~$1,100 recent reference |
| Terbium oxide | 6,585–6,645 | $987.75–996.75 | ~$4,000 recent reference |
| Yttrium oxide | 58–62 | $8.70–9.30 | Severe scarcity episodes; highly distorted |
| Holmium oxide | 631.9–651.9 | $94.79–97.79 | Thin/bespoke |
| Erbium oxide | 661.9–681.9 | $99.29–102.29 | Thin/bespoke |
| Thulium oxide | 762.7–782.7 | $114.41–117.41 | Very thin/bespoke |
| Ytterbium oxide | 92–112 | $13.80–16.80 | Very thin/bespoke |
| Lutetium oxide | 4,950–5,150 | $742.50–772.50 | Extremely thin/bespoke |
*Using ¥1 = $0.15 as requested.
Two Markets—Neither Is Truly a Market
China's quotations are not Western-style price discovery: quotas, licensing, state enterprises, industrial policy, and export controls shape the market. CREIA itself says its figures are industry-collected reference prices. But “ex-China spot” deserves equal skepticism. Transactions are sparse, bilateral, specification-sensitive, and confidential. Pricing agencies necessarily extrapolate from limited observations. A trader quotation is evidence of a transaction opportunity—not necessarily evidence of a market-clearing price.
REEx has previously tracked Dy around $1,100/kg and Tb around $4,000/kg outside China; USA Rare Earth's own SEC materials cite approximately those levels. Yttrium has experienced even more extreme scarcity dislocations, demonstrating why a $9 Chinese reference can become nearly meaningless to a Western buyer unable to access Chinese supply.
Washington is beginning to recognize that economics are the problem. The Pentagon's $110/kg NdPr floor for MP Materials is a specific 10-year contractual protection, not a universal U.S. price. Serra Verde's separate 15-year arrangement establishes $575/kg Dy and $2,050/kg Tb floors, again transaction-specific rather than industry benchmarks.
REEx takeaway: The West is beginning to construct answers for NdPr, Dy, and Tb. It still lacks a convincing commercial architecture for the long tail of exotic rare earths. That may become the next chokepoint after magnets.
Pricing qualifier: China and ex-China figures are not directly interchangeable. Purity, chemical form, qualification, provenance, volume, delivery point, licensing, and contract duration can radically change realizable prices. For thin exotic heavies, the absence of an executable offer may be more meaningful than a published quotation.
Source disclaimer: CREIA is a Chinese national industry association, not a state-owned enterprise or state-owned media outlet. Its published prices should nevertheless be independently verified given China's state-directed rare-earth system and CREIA's institutional environment.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →