
Highlights
- South Korea has established a national resource security council—an interagency control tower—to monitor and manage disruptions across critical mineral supply chains for EVs, batteries, and semiconductors.
- The initiative signals Korea's pivot from dependence-management to power-projection, moving beyond assuming global mineral market stability to preparing for sustained geopolitical turbulence.
- Investors should watch Korea's deployment of three key levers:
- Stockpiling heavy rare earths during China's export restrictions.
- Backing domestic magnet plants.
- Partnering with US, Australian, and ASEAN upstream projects.
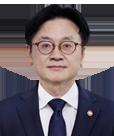
South Korea has unveiled a national resource security council—an interagency “control tower” designed to monitor and manage disruptions across mineral supply chains. The launch, led by Industry Minister Kim Jung-kwan (opens in a new tab), is not a symbolic bureaucratic reshuffle. It is a structural shift in how a major technological economy intends to navigate an era defined by rare earth scarcity, geopolitical risk, and intensifying U.S.–China competition.
Table of Contents
For investors, this signals something simple but consequential: Korea is no longer assuming global stability in the mineral markets that underpin EVs, batteries, motors, AI hardware, and semiconductor manufacturing. It is preparing for sustained turbulence.
Jung-Kwan Kim
What’s Real: The Facts Behind the Announcement
The core elements of the Yonhap report are accurate and consistent with Korea’s policy trajectory:
- Creation of an interagency resource-security council aligns with Korea’s Critical Minerals Strategy and recent KRW expansions of stockpile budgets.
- A crisis-alert system and public–private response framework reflect Korea’s recognition that private industry often feels disruption first—particularly battery giants like LG Energy Solution, Samsung SDI, and SK On.
- Expanded petroleum and critical mineral reserves match known efforts to reduce import concentration, especially for cobalt, nickel, and heavy rare earths.
- Support for overseas resource development echoes ongoing Korean partnerships in Australia, Indonesia, and Kazakhstan.
These are verifiable, non-speculative commitments.
Where the Story Stretches: Strategic Ambition vs. Practical Limits
The article suggests Korea will “boost participation in overseas resource projects.” True—but Korea has struggled historically to secure upstream equity, frequently losing to Chinese SOEs on cost, speed, and geopolitical access.
Similarly, establishing “biofuel infrastructure” is real policy but largely unrelated to mineral security—an example of bureaucratic bundling more than REE strategy.
Why It Matters: REE Security Is Leaving the Defensive Posture
Here’s the market-moving insight: Korea is pivoting from dependence-management to power-projection. EV and battery OEMs rely overwhelmingly on China for heavy rare earth separation and magnet-grade materials. A national control tower indicates that Korea sees the threat mounting—not hypothetical, not academic, but kinetic.
Investors should watch how this council deploys three levers:
- Stockpiling HREEs during China’s export-license slowdown.
- Backing Korean magnet plants (e.g., Vacuumschmelze Korea) seeking non-China alloy feedstock.
- Partnering with U.S., Australian, and ASEAN upstream projects to diversify the pipeline.
In a tightening world, Korea is declaring it will not be caught unprepared.
© 2025 Rare Earth Exchanges™ – Accelerating Transparency, Accuracy, and Insight Across the Rare Earth & Critical Minerals Supply Chain.


0 Comments
Discuss this article