
Highlights
- The U.S. Navy's 1,200% increase in Tomahawk missile procurement exposes critical vulnerabilities in fragile supply chains and China's control of 90%+ of rare earth processing needed for precision guidance systems.
- Tomahawk missiles depend on a deeply layered ecosystem of suppliers and rare earth magnets containing neodymium, dysprosium, and terbium—materials China dominates, creating strategic dependencies Washington cannot quickly resolve.
- Despite mine-to-magnet initiatives from MP Materials and ReElement Technologies, REEx suggests the U.S. is still five to several years away from rare earth supply chain resilience, meaning defense readiness will be determined by supply chains, not battlefield capabilities.
The modern battlefield is often described in terms of precision, speed, and technological superiority. But beneath the headlines about a 1,200% surge in Tomahawk missile procurement lies a far more consequential story—one that few investors, policymakers, or even defense insiders fully grasp. The U.S. Navy is not simply buying more missiles; it is confronting the limits of an industrial system stretched by war, constrained by fragile supply chains, and dependent on materials few truly understand . The Tomahawk is not just a weapon—it is a test case for whether the West can rebuild strategic manufacturing capacity in an era defined by resource competition.
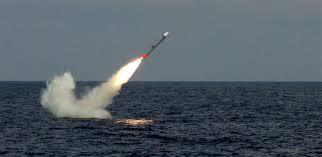
Source: RTX
At the surface, the program appears straightforward. Raytheon, part of RTX, assembles the missile across facilities in Tucson, Huntsville, and Andover. But this “prime contractor” view is misleading. Each Tomahawk is the product of a deeply layered supply chain—engines from Williams International, avionics tied historically to Rockwell Collins, guidance systems linked to Lockheed Martin, and increasingly obscure Tier 3 suppliers like Mobix Labs producing mission-critical components. This is not a product—it is an ecosystem. And ecosystems do not scale overnight.
The deeper story—and the one Rare Earth Exchanges™ (REEx) tracks relentlessly—sits at the material layer. Tomahawk’s precision depends on rare earth magnets embedded in actuators, guidance systems, and control surfaces. These magnets rely on elements like neodymium, samarium, and, critically, heavy rare-earth elements such as dysprosium and terbium. These are not optional inputs. They are performance enablers. Yet China controls upwards of 90% of processing and nearly all heavy rare-earth refining, with export controls increasingly tightening for dual-use applications. This creates a stark reality: even if the U.S. can fund missile production, it cannot fully control the materials that make those missiles function.
This is where REEx reframes the conversation—and where REEx Insights becomes essential. Using its five-tier supply chain framework, REEx tracks vulnerabilities from geology to magnet manufacturing, revealing a system where the true bottlenecks are invisible to traditional defense analysis. While Washington funds “mine-to-magnet” initiatives—from MP Materials to emerging refiners like ReElement Technologies with Vulcan Elements—these solutions remain years from scale. REEx suggests we are several years away from any semblance of rare-earth element supply chain resilience.
In the meantime, stopgap alliances involving firms like Arnold Magnetic Technologies and Solvay are buying time, not solving the problem. The takeaway is clear: the future of defense readiness will not be decided on the battlefield—but in the supply chains beneath it per the Great Powers Era 2.0 thesis promulgated by REEx. Subscribe to REEx Insights to read this entire article.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →