
Highlights
- China's Commerce Minister Wang Wentao is in Brussels for talks on export controls that impact global clean-tech and defense supply chains.
- 40% of license applications face unexplained delays.
- The April 2025 licensing regime affects industries from wind turbines to headphones.
- This exposes vulnerabilities in supply chains that depend on China's 90% dominance in rare-earth refining capacity.
- Despite temporary suspension after the Xi-Trump summit, Beijing's strategic controls give it powerful leverage over global manufacturers.
- This leverage forces companies toward diversification and onshoring strategies.
China’s Commerce Minister Wang Wentao (opens in a new tab) arrived in Brussels this week for talks with EU officials on Beijing’s tightening export controls over rare earth elements — a pivotal issue shaping the global clean-tech and defense supply chains. These controls, first implemented in April 2025 and broadened in October, continue to ripple across industries from magnets and motors to headphones and wind turbines.
Table of Contents
During her reporting for NRC (opens in a new tab), Tabitha Speelman captured the real-world implications through the eyes of Aaron R. Berg, MSc., a sales manager at a Dutch SME that imports permanent magnets from China. Berg, who oversees hundreds of export-license applications, described the process as “bureaucratic, opaque, and unpredictable.” While on holiday in Beijing, he even visited the Ministry of Commerce building on Chang’an Avenue — a stark symbol of how deeply global manufacturers are now entangled in China’s administrative machinery.
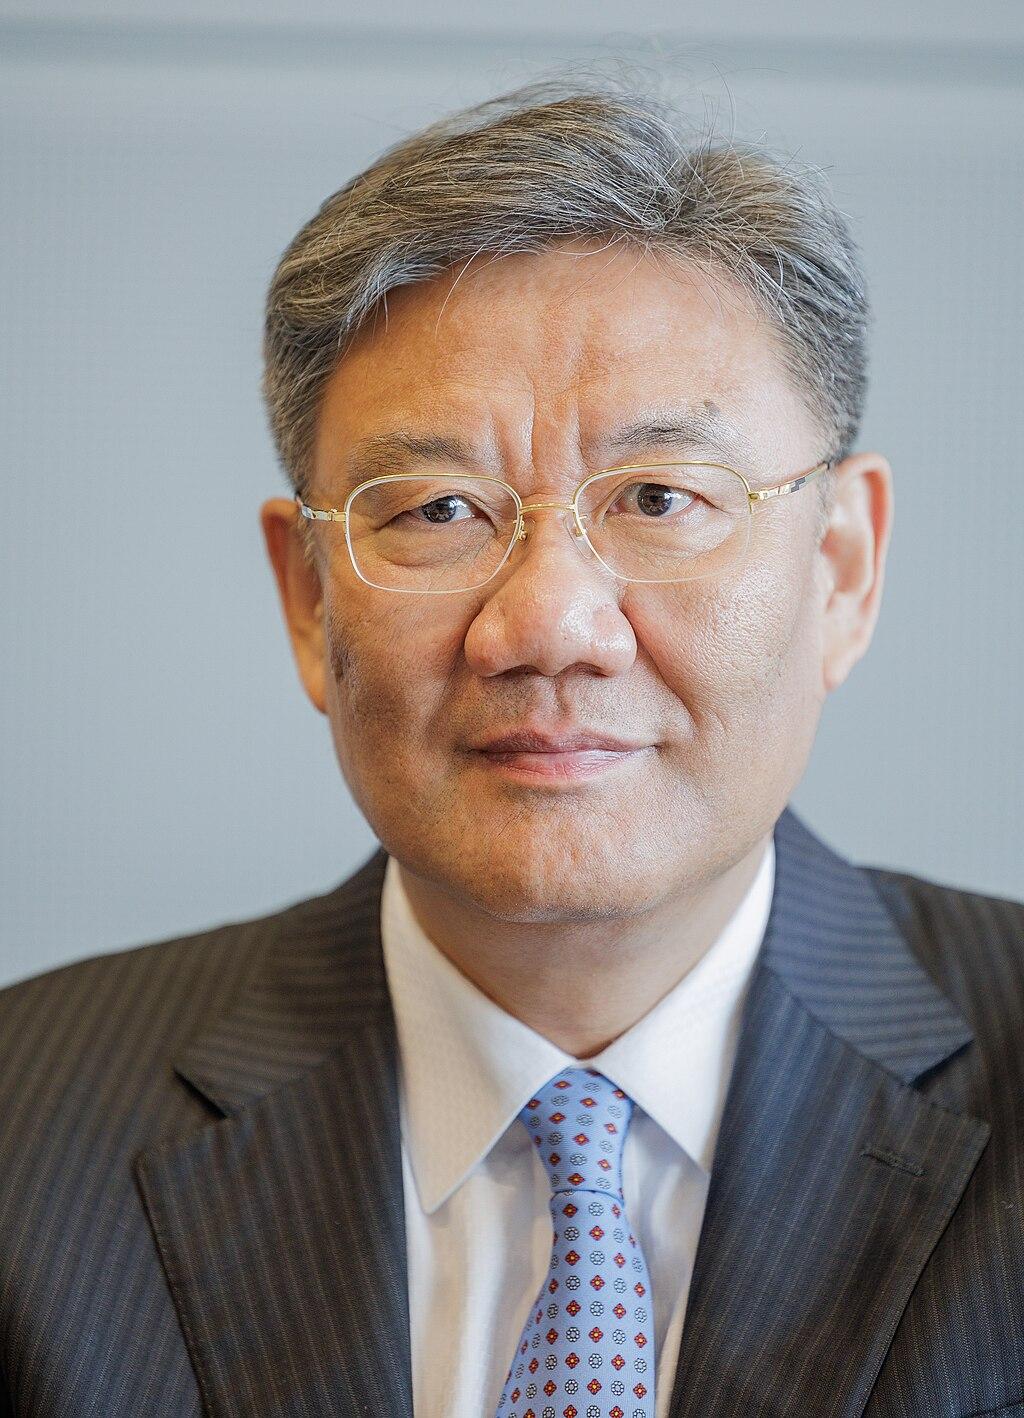
Wang Wentao, Commerce Minister
The Facts Please
- Scope and dominance: China accounts for roughly 90 % of global rare-earth refining and separation capacity, according to the IEA.
- Controls introduced: The April 4, 2025, rules require export licenses for seven heavy rare-earth elements and related products.
- Industry impact: Even low-tech sectors like appliances and audio equipment are ensnared, not just aerospace or semiconductors.
- Administrative strain: Roughly 40 % of applications, per Berg’s firm, face long delays with no clear reason — highlighting the bottleneck risk.
Reading Between Those Lines
Speculation around a proposed “white list” of longer-term licenses remains unconfirmed. Analysts’ optimism that Brussels talks will yield relief seems premature; Beijing’s export-control expansion is strategic, not accidental. Berg’s comment that “China is getting really smart this way” underscores another reality — these filings hand over detailed supply-chain data, a subtle yet powerful information advantage.
Investors—Why do we care?
For magnet and motor producers, this is not paperwork — it’s geopolitics in triplicate. The licensing regime exposes the world’s reliance on China’s discretion, nudging OEMs toward diversified sourcing, stockpiling, and onshoring. A temporary suspension, announced after the Xi-Trump summit, offers respite, not resolution.
So what’s that bottom line? Brussels may signal dialogue, but Beijing still holds the lever. The rare-earth trade remains one of China’s most potent strategic tools — and for global investors, that means the era of passive dependence is over.
Citations: IEA (2025) Commentary: With New Export Controls on Critical Minerals, Supply Concentration Risks Become Reality; NRC, Reporter: Tabitha Speelman.
©!-- /wp:paragraph -->


0 Comments
Discuss this article