
Highlights
- China is expanding germanium production through Yunnan Lincang Xinyuan's verified 75-ton annual capacity increase, consolidating control over a critical mineral market that supplies fiber optics, defense systems, and semiconductors.
- U.S. germanium import reliance remains over 50% with virtually no domestic primary refining, while prices have spiked dramatically—from $5,380/kg to as high as $12,000/kg—exposing severe supply chain vulnerability.
- Western responses including Korea Zinc's Tennessee smelter and EU-backed projects face steep challenges, while impending DFARS compliance rules create additional chokepoints for defense contractors dependent on Chinese-controlled germanium processing.
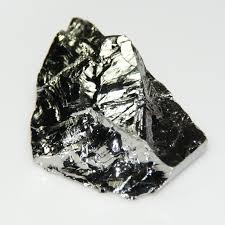
This report examines growing signs of a tightening global germanium market and evaluates a specific industry rumor that China is constructing a new 100-ton-per-year germanium facility. Rare Earth Exchanges™ could not verify any current 2025–2026 primary Chinese source confirming such a standalone project. However, what we did confirm may be equally important: Yunnan Lincang Xinyuan Germanium Industry Co., Ltd (opens in a new tab). is actively expanding production capacity equivalent to roughly 75 tons per year of contained germanium alongside additional downstream wafer manufacturing. In a market as small and strategically sensitive as germanium, that is material. Germanium remains a critical choke-point mineral underpinning fiber optics, infrared optics, satellites, defense imaging systems, solar technologies, and advanced semiconductor processes. The broader takeaway is not whether one massive new plant exists, but that China continues steadily tightening its dominance across the germanium value chain through incremental expansion, refining control, and downstream integration while the West still struggles to rebuild meaningful domestic processing capacity.
Market reality
Germanium output is unusually opaque. The latest detailed USGS yearbook says reliable world production data are scarce, but industry reports put 2023 supply at roughly 100,000–200,000 kg a year. China remains the leading producer and exporter; secondary sources used by USITC and Reuters put China at about 60% of world output in 2022. Germanium usually comes as a byproduct of zinc refining or coal ash. Commercial refining and recycling are concentrated in China, Belgium, Canada, Germany, Russia, and limited U.S.facilities. Main end uses are fiber optics, infrared optics,semiconductors/germane gas, solar cells, and PET catalysts.
The United States consumes approximately 30 to 40 metric tons of Germanium per year. This essential critical mineral drives high-tech industries, with national demand primarily split between fiber-optic systems, infrared optics for defense and aerospace, polymerization catalysts, and solar cells.
Why U.S. access is weak
The U.S. still lacks meaningful primary refining from domestic concentrates. USGS says Alaska’s germanium-bearing zinc concentrate goes to Canada for recovery, Tennessee mining has been suspended since late 2023, and U.S. processors in Utah and Oklahoma rely on imported or recycled feed. U.S. net import reliance remains over 50%. China’s 2023 licensing regime for germanium exports is still in force, and although Beijing suspended its 2024 U.S.-specific “principally no licenses” clause until November 27, 2026, the gatekeeping power remains in Chinese hands.
Any Large Projects?
The closest current verified Chinese project is Yunnan Lincang Xinyuan Germanium. Its 2025 annual report says its “advanced germanium materials” project will add 45 t/y high-purity germanium tetrachloride, 15 t/y high-purity germanium dioxide, and 50 t/y zone-refined germanium ingot, equivalent to roughly 75 t/y of contained germanium. A May 2025 Lincang government entry confirms a project progress meeting. I found one old 2008 Inner Mongolia government note referencing 100 t/y of “germanium-seriesproducts,” but that is not evidence of a new currentfacility. A separate 2024 Reuters report about rumored state buyingof 100 tons appears to be stockpiling chatter, not plant construction.
China’s push and the Western response
China is still consolidating power through policy, not just tonnage. China’s Ministry of Commerce (MOFCOM) export controls remain the central lever. Yunnan’s 2026 industrial plans explicitly call for extending silicon-germanium-indium value chains into downstream semiconductors, while National Natural Science Foundation of China (NSFC) is funding low-grade germanium coal recovery, isotope work, and 12N–13N purification research.
Key names and contact trails: Yunnan Lincang Xinyuan Germanium (Kunming office; board secretary Zhang Xinchang listed in filing), Yunnan Chihong Zinc & Germanium (state-backed Yunnan producer), Korea Zinc (Seoul; official IR/contact page), Teck (Vancouver; official contact page), Nyrstar (Budel; official contact page), and Umicore (Brussels; journalist/investor contact pages).
Western responses include Korea Zinc’s Tennessee smelter plan, Nyrstar’s Clarksville Ge/Ga recovery concept, Umicore’s EU-selected germanium projects, and U.S. Defense/DOE support for 5N Plus and byproduct recovery. Payne Institute’s core recommendation fits germanium exactly: recover and process more byproducts domestically. Treat all company language such as “world-leading” or “transformational” as promotional until permits, feed contracts, EPC, commissioning, and customer qualification are proven.
Investor implications
For investors, germanium is a low-volume, high-leverage choke point. Supply risk stays high because output is opaque, licenses are political, and price spikes can be violent; USGS shows European germanium metal prices rising to about $5,380/kg in October 2025. According to a trader on condition of anonymity a kg can go for $12,000 now, or even more.
Opportunity sits in byproduct recovery, recycling, allied refining, and substitution in infrared optics. Due diligence should ask five questions: what is the contained-germanium capacity, where is feedstock contracted, what export licenses are actually clearing, what is the capex/startup schedule, and who are the qualified end customers?
And what about the imminent Defense Federal Acquisition Regulation Supplement (DFAR) rules? For companies operating inside the U.S. defense industrial base, navigating the DFAR often comes down to two possible pathways: qualifying for a built-in statutory exemption or securing a formal government waiver. Exemptions are generally the simpler and more practical route because they are already embedded in the regulation itself. These commonly apply to Commercial Off-The-Shelf (COTS) products or materials sourced from allied nations covered by reciprocal procurement agreements. In those cases, contractors typically only need sufficient documentation proving eligibility.
Waivers, by contrast, are far more difficult, political, and heavily scrutinized. They are typically pursued only when compliance is impossible, prohibitively expensive, or potentially harmful to national security—such as shortages involving specialty metals, semiconductors, rare earths, yes germanium, or constrained supply-chain inputs.
Approval often requires senior Pentagon-level signoff. As geopolitical tensions rise and China tightens control over strategic minerals and processing, DFARS compliance now becomes a growing chokepoint across semiconductors, defense electronics, rare earth magnets, and critical materials supply chains.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →