
Highlights
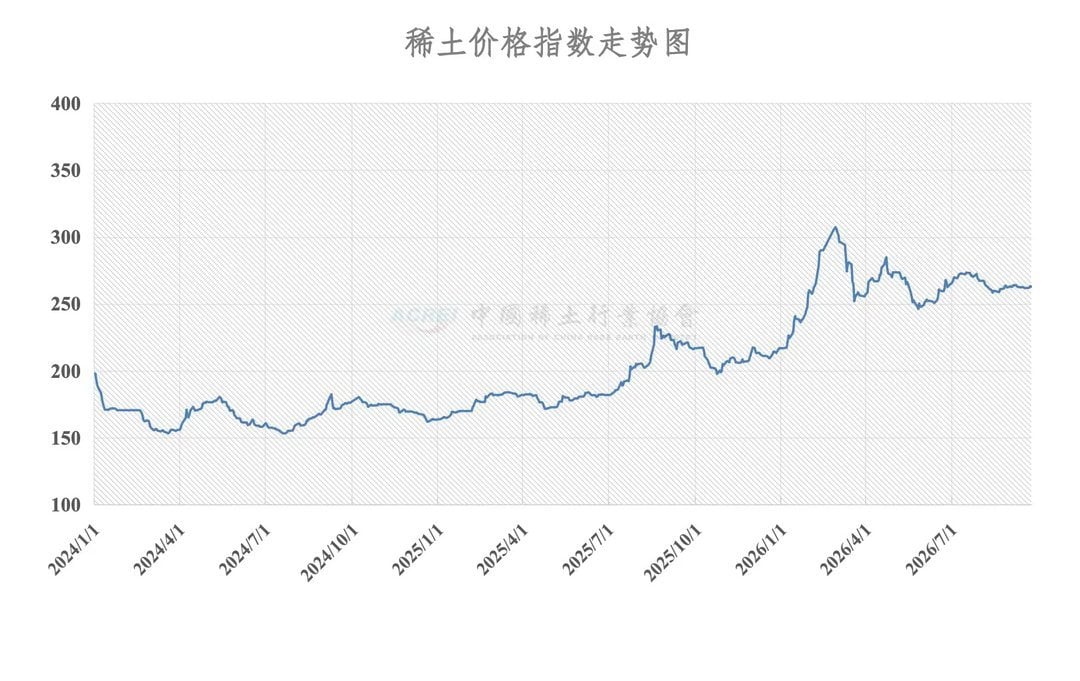
- China's CREIA September 23 Rare Earth Price Index stands at 262.9, with dysprosium oxide at ~$214/kg domestically versus $3,250/kg in a recent North American transaction.
- Terbium oxide trades at roughly $7,500/kg in North America—about 7.5× the Chinese domestic reference of ~$992/kg.
- Government-backed price floors like the Pentagon's $110/kg NdPr deal with MP Materials are contractual minimums, not universal market prices.
- Yttrium highlights a new pricing reality: when material is unavailable due to export restrictions, a listed price of $9/kg is effectively meaningless.
- Rare earth pricing now reflects chemistry, provenance, export permission, qualification, and inventory—not conventional commodity market discovery.
China’s Rare Earth Industry Association (CREIA) reported its September 23, 2026 Rare Earth Price Index at 262.9, with 2010=100. Domestic prices appear remarkably calm: dysprosium oxide is ¥1,410–1,450/kg ($211.50–$217.50) and terbium oxide ¥6,585–6,645/kg ($987.75–$996.75). But in North America, S&P Global (opens in a new tab) reports actual September trades at $3,250/kg for Dy oxide and $7,500/kg for Tb oxide—roughly 15× and 7.5× the respective midpoint China references. The investor takeaway: rare earths increasingly have different prices depending on geography, origin, export permission, qualification, and whether material is physically available at all.
REEx Insight: Price Is Becoming a Function of Permission
Welcome to Great Powers Era 2.0™ price discovery. China’s CREIA quotations are useful domestic reference signals, but they should not be confused with exchange-cleared global prices. China's rare-earth ecosystem operates amid production controls, export licensing, state-owned producers, industrial policy, and national-security objectives. Reuters reports China still controls more than 85% of rare-earth refining and production.
But the West does not have clean price discovery either. Ex-China trades remain thin, OTC, bilateral, and frequently confidential. Purity, provenance, qualification, quantity, freight, financing, contract duration and—critically—available inventory can radically alter a transaction.
That makes pricing-agency assessments valuable signals, but not gospel. An assessment assembled from a small number of traders or transactions is fundamentally different from thousands of bids and offers clearing on an exchange. REEx has been tracking precisely this “market behind the market.”
The September 23 Fault Line
China conversions use the requested ¥1=$0.15. Ex-China figures deliberately distinguish published indications, contractual floors, and actual transactions.
| Strategic product | China ¥/kg | China $/kg | Ex-China evidence |
|---|---|---|---|
| NdPr oxide — magnet LREE | ¥724.1–744.1 | $108.62–111.62 | ~$140 non-China indication; MP has $110 floor |
| Dysprosium oxide — magnet HREE | ¥1,410–1,450 | $211.50–217.50 | ~$1,100 indication; $3,250 Sept. N.A. trade |
| Terbium oxide — magnet HREE | ¥6,585–6,645 | $987.75–996.75 | ~$4,000 indication; $7,500 Sept. N.A. trade |
| Yttrium oxide — strategic HREE-associated | ¥58–62 | $8.70–9.30 | No defensible liquid benchmark; availability can dominate price |
| Samarium oxide — SmCo magnets | ¥163–183 | $24.45–27.45 | Thin/bespoke; strategically important for high-temperature SmCo magnets |
The ~$1,100 Dy, ~$4,000 Tb, and ~$140 Nd/Pr non-China indications come from USA Rare Earth investor materials; importantly, they are references, not universal executable prices. The $3,250 Dy transaction involved legacy Chinese-origin material exported before restrictions—another reason not to extrapolate one trade into a market benchmark.
Yttrium: When “How Much?” Becomes “Can I Get It?”
Yttrium demonstrates why price sheets can mislead. China lists oxide around $9/kg, yet Reuters reports persistent supply constraints are forcing aerospace suppliers to investigate alternative turbine-coating materials. China retains near-monopoly leverage over the supply. For procurement officers, an unavailable $9 material does not cost $9. It has no executable price. That distinction increasingly applies to Dy and Tb as well. Reuters reported this month that some Chinese rare-earth suppliers had halted certain U.S. shipments and that licensing delays continued to constrain critical materials.
Floors Aren’t Spot Prices—and $110 Is Not Necessarily “The U.S. Price”
Another source of investor confusion is government-backed price floors. The Pentagon's MP Materials agreement guarantees $110/kg for NdPr for 10 years. That is a contractual price-protection mechanism for MP—not a government decree establishing $110/kg as the market price for every American producer. MP itself describes compensation when its benchmark price falls below $110. Serra Verde makes the distinction even clearer. Its U.S.-backed arrangement contains floors of $575/kg Dy, $2,050/kg Tb, and $110/kg each for Nd and Pr. Yet USA Rare Earth simultaneously presented non-China indications around $1,100 Dy and $4,000 Tb.
A floor therefore tells investors something important about the minimum economics governments are willing to underwrite. It does not tell buyers what tomorrow's scarce kilogram costs.
REEx Bottom Line: There Is No Single Rare-Earth Price
The 262.9 index is useful—but the more important signal is the widening gulf between Chinese domestic reference value and Western replacement cost. For light rare earths such as NdPr, that gap remains manageable. For Dy, Tb, and Y, the equation has changed: Price = chemistry + provenance + qualification + inventory + export permission + geopolitics. That is not conventional commodity price discovery. It is strategic-material allocation—and one of the defining economic features of Great Powers Era 2.0.
Source & pricing disclaimer: CREIA is a Chinese national rare-earth industry association, not a state-owned enterprise. Its September 23 figures are industry-collected domestic reference data and should be independently verified. Ex-China figures likewise are not universal spot prices: rare-earth transactions are frequently confidential, specification-dependent, and illiquid. Individual transactions, government-supported floors, and pricing-agency assessments should never be treated interchangeably.
REEx prior analysis: Ex-China Rare Earth Pricing: The Market Behind the Market | Dysprosium/Terbium: China vs. Ex-China Price Divide | Yttrium and the Fractured Global Market


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →