
Highlights
- South Korea and China signal cooperation on critical mineral supply chains, but the power balance is asymmetric—China controls 85–90% of rare earth processing, 90%+ of permanent magnet production, and 95–98% of heavy rare earth separation capacity.
- The diplomatic language of “stable” and “predictable” access masks structural imbalance—no mention of China’s 2025 export controls, licensing uncertainty, or Korea’s lack of ex-China supply chain alternatives.
- Supply chain stability is not market-driven but policy-mediated: until ex-China rare earth separation scales materially, Korea’s industrial base remains dependent on negotiated access, not secure supply.
In a world tightening around minerals—not markets—South Korea and China are signaling cooperation, at least on paper. The report notes both countries reaffirmed the need for “stable supply chains” for critical minerals and rare earths amid global uncertainty. To keep it simple: South Korea, heavily dependent on imported processed materials, is seeking predictable access, while China is signaling willingness to maintain flows under its terms.
Diplomacy or Dependence? Follow the Material
This framing via The Korea Herald (opens in a new tab), is largely accurate—but the power balance is not neutral.
South Korea’s industrial base—semiconductors, EVs, batteries—relies on supply chains where China dominates:
- ~85–90% of rare earth processing (not just refining—important nuance)
- ~90%+ of permanent magnet production (varies by segment; often higher in NdFeB)
- ~95–98% of heavy rare earth separation capacity
This is not partnership parity. It is asymmetric interdependence tilted toward China.
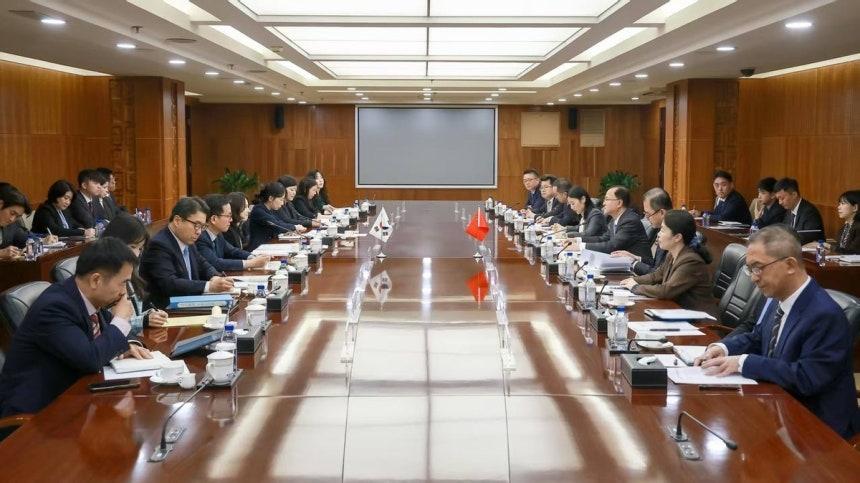
Source: The Korea Herald
What’s Said… and What’s Carefully Not
The language—“stable,” “predictable,” “mutually beneficial”—is classic diplomatic signaling, not operational detail.
What’s omitted is more telling:
- No reference to China’s export control regime (tightened in 2025)
- No mention of licensing uncertainty or end-use restrictions
- No indication that Korea is reducing dependency via ex-China supply chains
Stability here is not market-driven—it is policy-mediated access.
Signal vs. Substance: The Polite Fiction
There is no outright misinformation—but there is narrative softening. The article frames cooperation as balanced, when the underlying reality is structural imbalance.
China controls the midstream. Korea depends on it.
Why This Matters: Access Is the Real Battlefield
This is not a routine bilateral meeting. It is a quiet admission: supply chain wars are decided by who controls processing, not who signs communiqués.
China remains the system anchor. Korea is hedging within that system—not exiting it.
Bottom line: Until ex-China separation—especially heavy rare earths—scales materially, “stability” is not a market condition. It is a negotiated outcome.


0 Comments
No replies yet
Loading new replies...
Moderator
Join the full discussion at the Rare Earth Exchanges Forum →